CivicScience has the world’s largest proprietary database of real-time declared intent, allowing brands to activate high-performing advertising that drives up to 80% better performance. See how CivicScience partners achieve superior marketing outcomes here.
The changing of the seasons brings retail sales events as the holiday season rapidly approaches. Amazon Prime Big Deal Days (BDD), happening October 6-7, is one of these marquee early-season shopping events. CivicScience has been tracking this sale for years and has the latest in consumer-reported data as Prime members look ahead to another 48 hours of deal hunting.
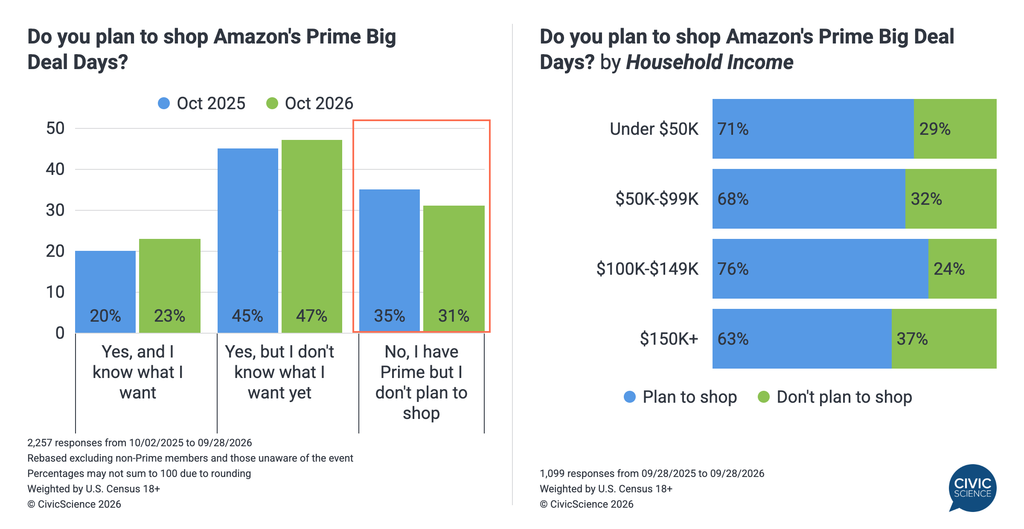
The latest data suggest that intent to shop Big Deal Days is on the rise. Last fall, 65% of aware Prime members told CivicScience they planned to shop during BDD 2025. That percentage is now up to 69%, and includes 23% who are already set on exactly what they’re looking to buy.
Shopping intentions span generational lines, though interest is strongest among consumers under 45 — 78% of Gen Z and 70% of Millennial Prime members plan to shop the event. Still, the event isn’t limited to younger shoppers, as a majority of Gen X (66%) and Baby Boomer (59%) Prime members also intend to hunt for deals.
There are also interesting splits when examining sale intent by income. Prime members earning $100K-$149K are the most likely to shop BDD 2026, followed by those earning less than $50K. Higher-income individuals (earning $150K+) are comparatively less likely to shop.
Beauty Buying Intent Surges
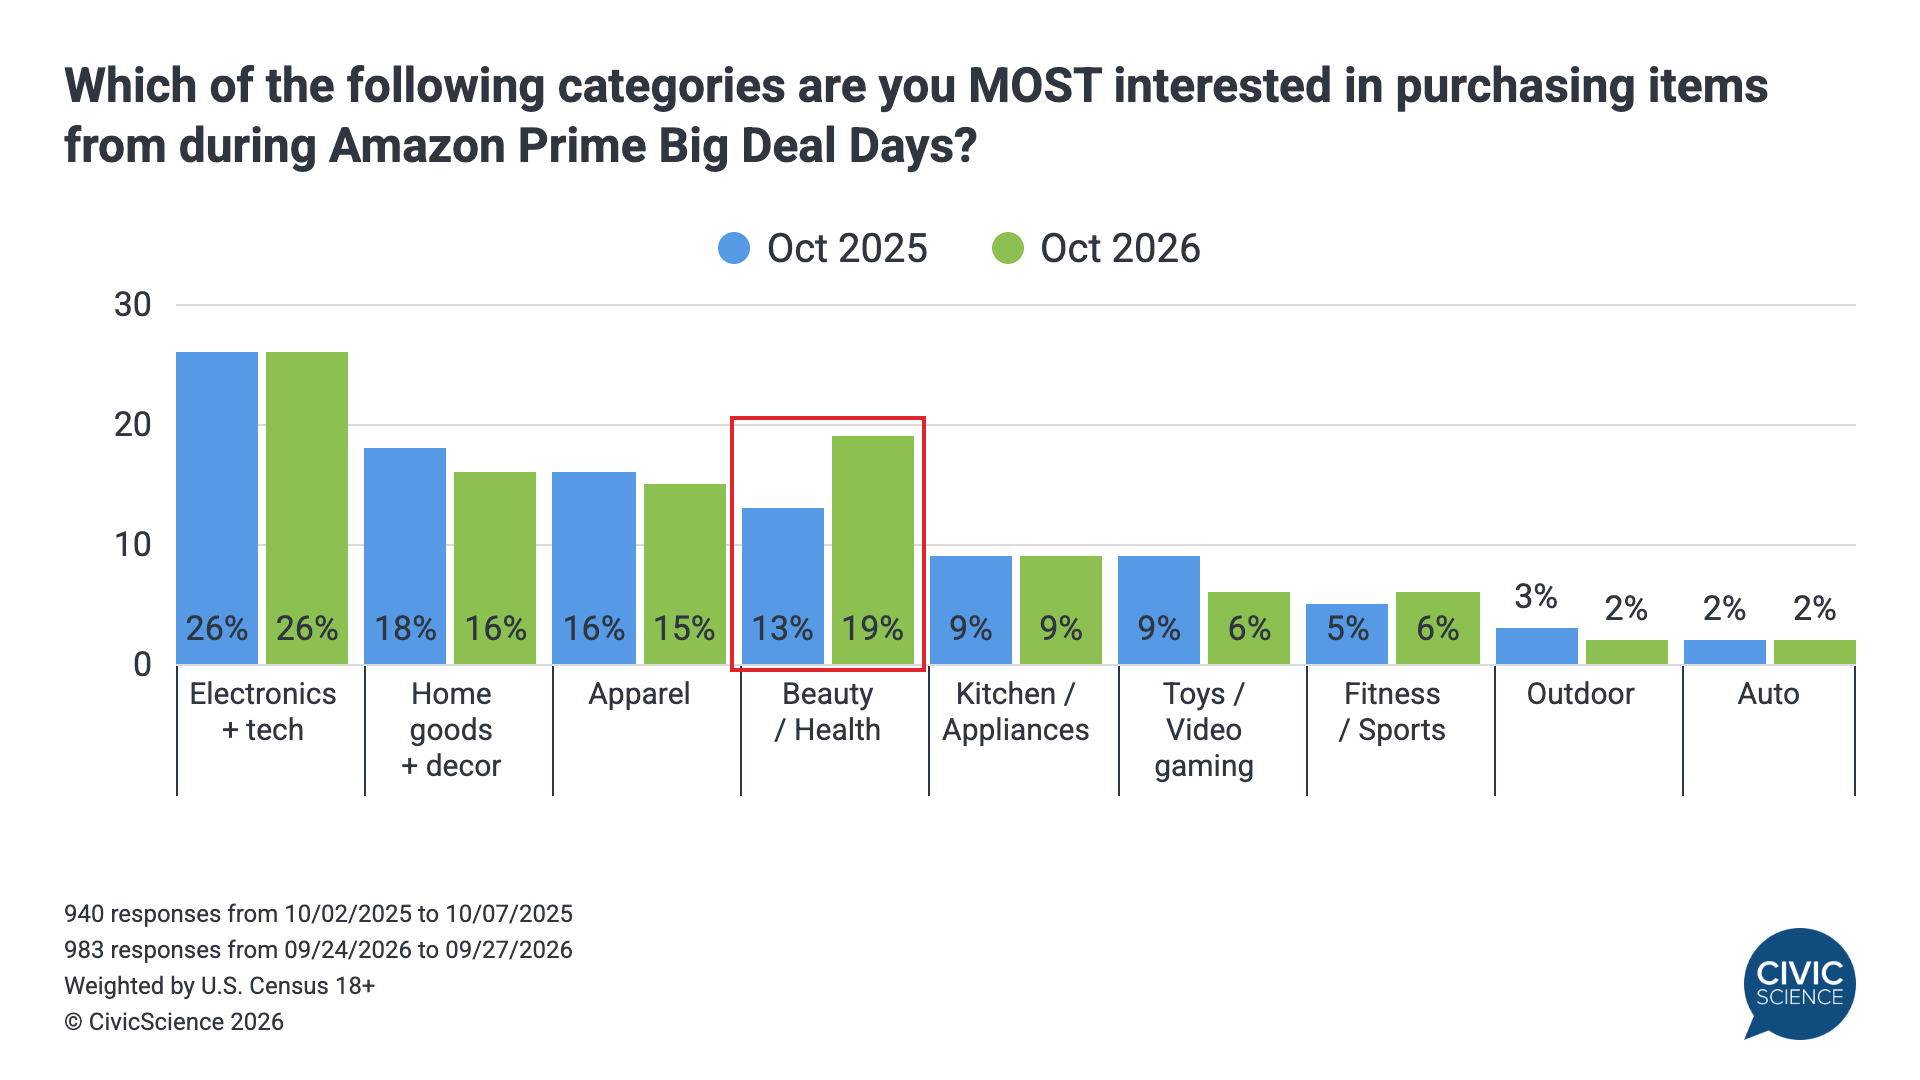
One of the more noteworthy trends this year is the growing interest in buying beauty products. Nearly 1 in 5 shoppers now say they’re most interested in shopping for beauty — a six-percentage-point increase compared to pre-2025 Big Deal Days. This upswing is enough to lift the beauty category from fourth to second in year-over-year interest. At the same time, the share of those looking to buy toys is down three points. Amid these shifts, electronics and tech remain the most sought-after category.
Gen Z shoppers are the biggest drivers of this rising beauty intent, with interest standing at 26% among them. Meanwhile, Gen Xers are the most likely to shop for electronics (31%), while Baby Boomers aged 65+ drive apparel demand (20%).
Beauty has proven a resilient category in the face of years of economic uncertainty. And it’s particularly important to this year’s BDD shopper — 58% of whom say they use beauty (such as skincare, hair care, or makeup) as a form of self-care at least ‘somewhat’ often (compared with 46% of U.S. adults overall among the average American). That practice is becoming more expensive amid the Iran War, making the sale a potentially enticing way to buy beauty at more affordable prices.
Where Holiday Shopping Fits In
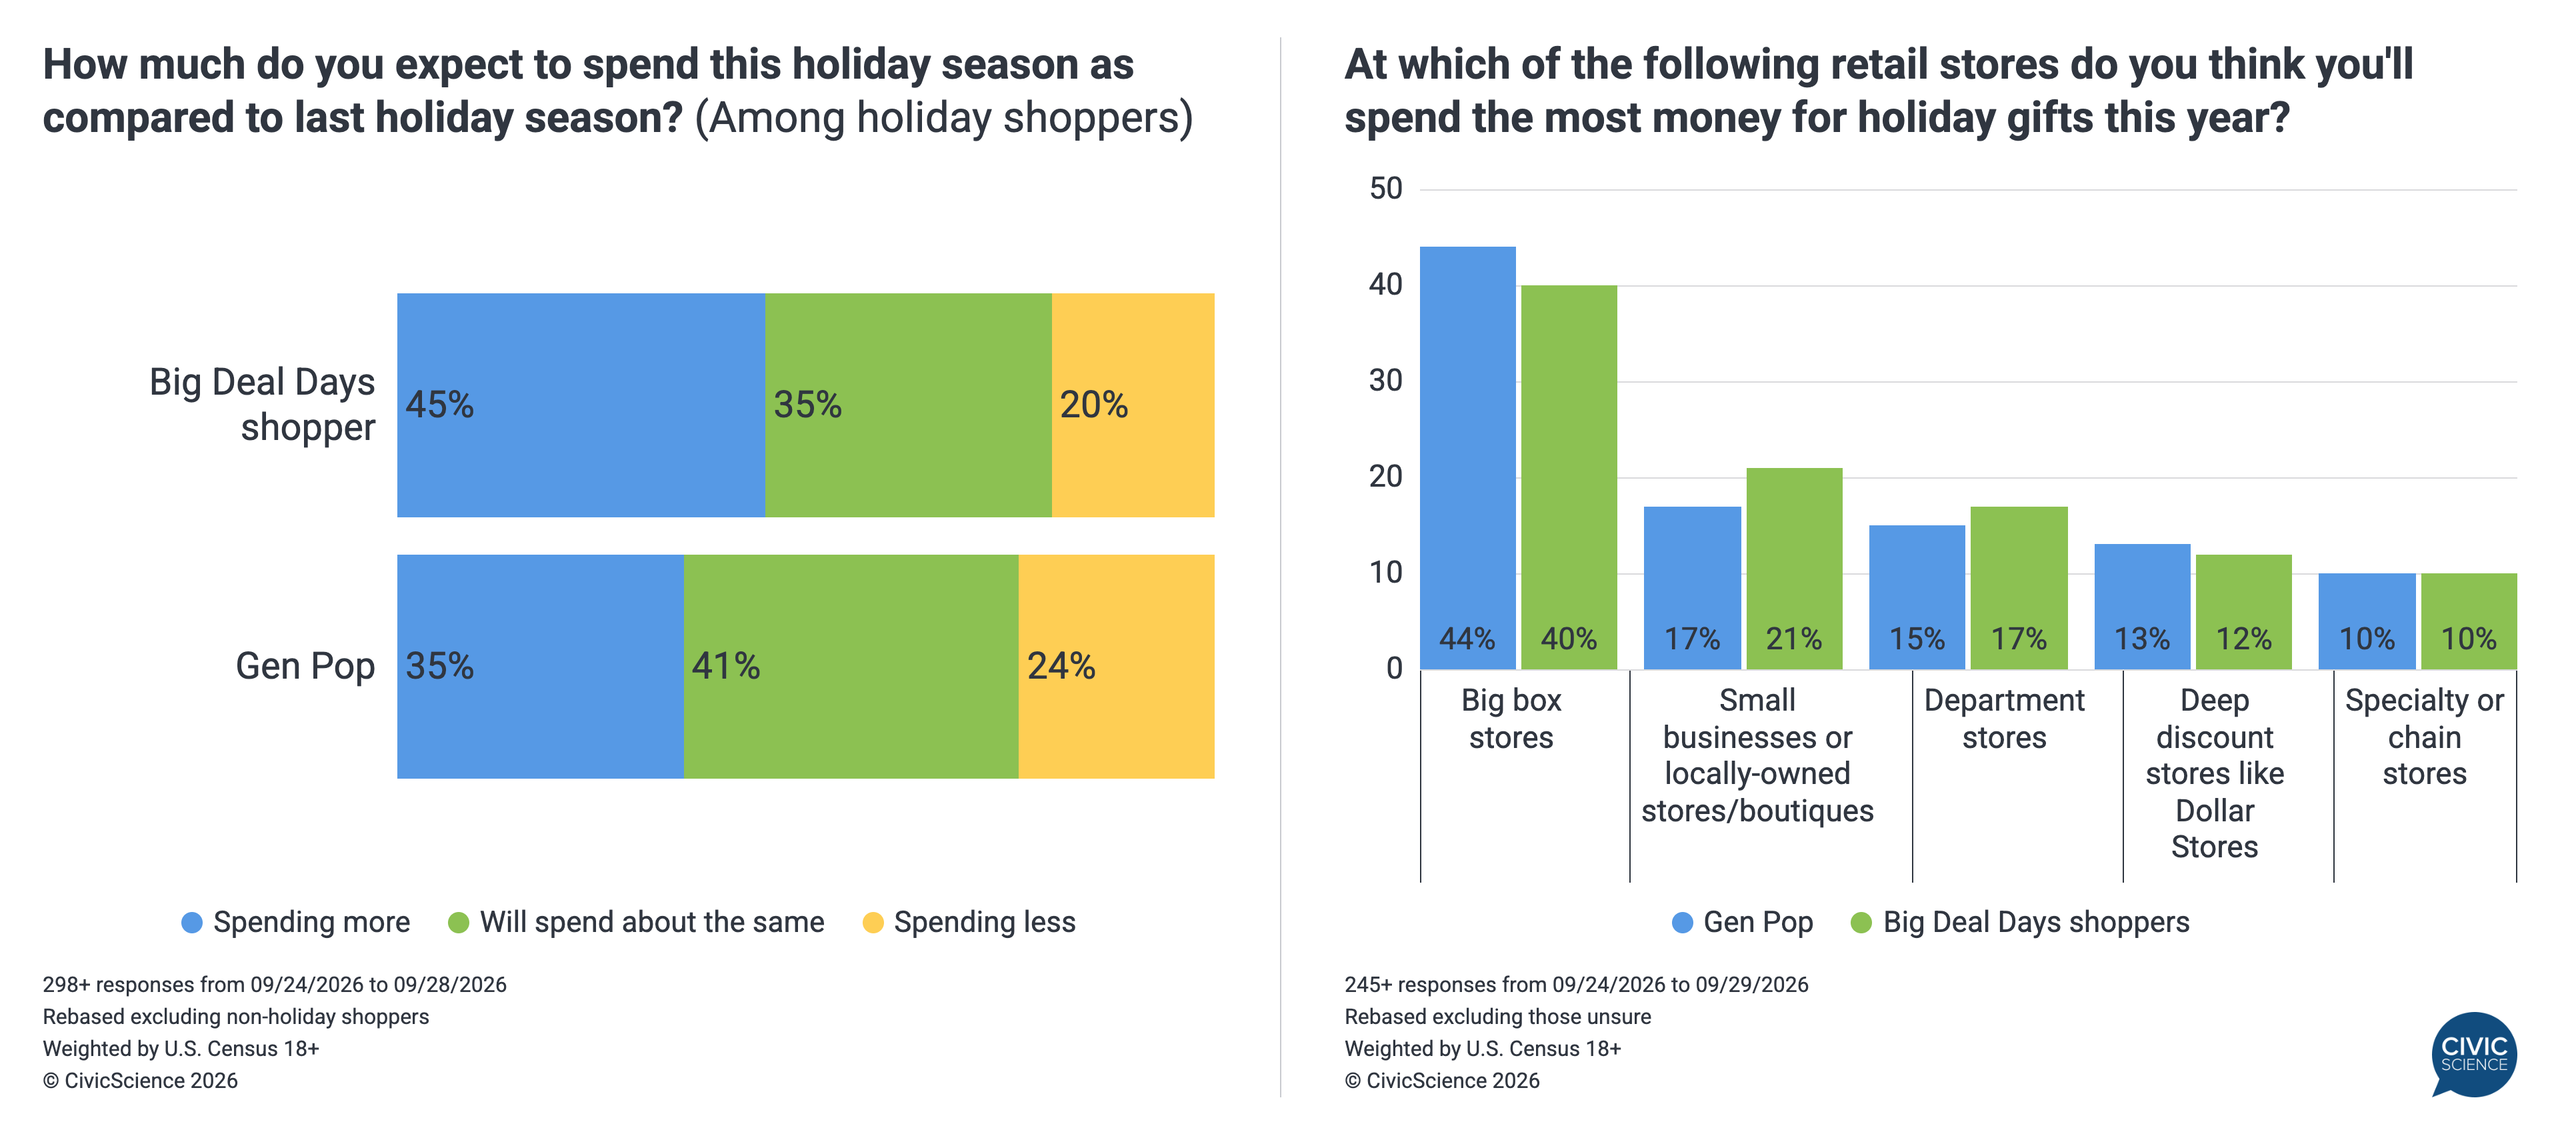
Big Deal Days intenders are also planning for a larger budget for the holiday season this year. Nearly half (45%) say they expect to spend more on the holidays, 10 percentage points higher than the average holiday shopper. With roughly a week until the sale begins as of this writing, 32% of BDD shoppers say they specifically plan to shop for holiday gifts during the Big Deal Days. That share may climb as the sale draws closer, with another 47% unsure whether they’ll take advantage of BDD deals for their holiday gifts.
Beyond timing their gift purchases around the sale, these shoppers also show distinct priorities in where they plan to spend the most. Big box retailers top the list at 40% of Big Deal Days shoppers, though that trails the Gen Pop at 44%. Instead, these deal hunters are more likely than average to name small businesses (21% vs. 17%) and department stores (17% vs. 15%) as where they’ll spend the most on gifts.
Big Deal Days offers a useful snapshot of where consumer priorities stand heading into the holidays. Shoppers are expecting to spend more, directing more interest toward personal categories like beauty, and looking beyond the largest retailers for gifts. With geopolitical tensions still in play, how closely those intentions hold through December will be worth watching.